
Land in the Sand at Morgans Noosa
Noosa retirees face the biggest tax shake-up in a generation. John Caruso discovers the answer is preparation, not panic.
At 7.30pm on 12 May, while most of us were clearing away the dinner plates, the federal budget drew a line through the middle of retirement planning. Investment property held or contracted by that minute kept its negative gearing. Almost everything else about retirement tax started to shift.
For a generation the arrangement was simple enough to explain over a coffee: build your super, move it into pension phase, and keep a separate pool of shares or property in your own name. With little other income, those personal assets could earn a fair sum each year and attract almost no tax at all. It was tidy, legal and dependable, and it’s now coming apart.
“They’re three of the most substantial tax changes we’ve seen in a long, long time,” Jonathon Laird says.
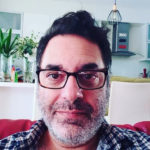
The financial planner at Morgans Noosa walked through all three changes in October for the Noosa branch of Australians in Retirement, a room full of people who had expected to be finished with the tax office.
“It’s a bitter pill to swallow when you’re not paying tax, and then suddenly you’re on the hook to pay a little bit more,” Jonathon says. “I totally get it.”
The change that cuts deepest for retirees is Capital Gains Tax (CGT). From 1 July 2027 the 50 percent CGT discount, a fixture since 1999, is replaced by cost-base indexation. Instead of halving a gain, investors lift the purchase price of an asset by inflation each year and pay tax on the real gain that remains. Eligible gains will also carry a minimum tax of 30 percent, regardless of the investor’s marginal rate.
That flaw is what unpicks the old arrangement.
“Retirees would have assets in their personal name because you can earn a fair amount of income or assessable gains and not pay tax, roughly around $30,000 a year,” Jonathon says. “This has changed the dial.”
The rules are not retrospective. Gains made before 1 July 2027 retain the existing 50 percent CGT discount. From that date, a new inflation-based method applies. For assets already owned at 1 July 2027, the eventual capital gain will therefore reflect a combination of both the old and new rules. His single most important piece of advice is practical and close at hand.
“Get a valuation of your investment property around 1 July 2027 and keep the evidence,” he advises. “This will help establish how much of the gain occurred before and after the new rules take effect.”
After 30 boom years in Australian property, and with the prospect of flat or even negative real growth over the next couple of financial years, the timing of that split carries real money.
“Having a reliable valuation will be important in establishing how much of the gain relates to the period before the new rules take effect,” Jonathon says.
The second change sits inside super itself: Division 296 is now law and applies from 1 July 2026. Balances up to $3 million keep their existing treatment; earnings attributable to the portion between $3 million and $10 million attract an extra 15 percent, taking them to as much as 30 percent.
Above $10 million, a further 10 percent applies, for up to 40 percent all up. The additional tax falls on earnings, not on the whole balance. The instinct may be to move investments elsewhere, but Jonathon asks where they would go. The new capital gains rules also apply to investments held personally, while companies already pay tax at up to 30 percent.
“The government is taxing super more; however superannuation is still an amazing wealth accumulation and retirement vehicle,” he says.
There is good news for couples. The $3 million threshold applies to each person, not to the household, so a lopsided arrangement where one spouse holds most of the super is worth a second look.
“If one spouse has the bulk of the superannuation and they’re approaching that $3 million mark, it may be worth considering strategies to better balance their super between them,” Jonathon says. “Why pay more tax if you don’t have to?”
The third change is still on paper. A proposed 30 percent minimum tax on discretionary trust income, due from 1 July 2028, exists only as an exposure draft. Trustees face three paths: keep full discretion and accept the tax; elect fixed distributions in exchange for a likely exemption; or restructure using a proposed three-year rollover window from 1 July 2027 that would let assets move without triggering CGT.
Jonathon says the key is to understand the options available and wait for the final legislation before making any major changes.
So, what are clients saying when they sit down with Jonathon and the team at Morgans Noosa?
“There’s a bit of fear, and there’s a bit of wait and see,” he says.
The question he hears most is blunt: How do we not pay tax?
Part of the answer is that there are still some levers available. Assets held in pension phase can continue to benefit from tax-free investment earnings, while investment strategies can also be adjusted depending on individual circumstances.
“What we can do is pivot the investment strategy,” Jonathon says. “For investments held outside super, there may be greater reason to consider income-focused investments, with that income taxed at the investor’s marginal tax rate.”
Political promises to wind the changes back draw a measured response. Some measures may be diluted through consultation, and a future government may or may not reverse them once the revenue starts flowing.
“Don’t bank on them being reversed and don’t make any knee-jerk structural changes to your financial position,” he says. “We’ve got a bit of time for any of these changes coming in, and you’ve got to assess the alternatives.”
For retirees watching the headlines, the work now is records, valuations and a clear view of how assets are held between spouses and structures. Jonathon would rather see clients now than in a rush in June 2027.
“Remember, you’re paying tax because you’ve made money,” he says.
This article contains general information only and does not take into account individual circumstances. Seek personal advice before acting.
Visit the website for more.